Paul Baran opened The Political Economy of Growth (1957) with a question that most development economists still refuse to take seriously: if peripheral economies generate an economic surplus–the difference between what society produces and what it needs to reproduce itself–why does so little of it translate into productive development? The surplus exists. In many cases, it represents a substantial fraction of national income. The obstacle is not scarcity. It is what the ruling classes do with what they extract.
Baran distinguished between the actual surplus–what is in fact saved and accumulated–and the potential surplus: what an economy could accumulate if the existing social order did not squander it. That squandering takes four forms: the excessive consumption of the propertied classes, unproductive labor, the irrational organization of production, and unemployment. In underdeveloped countries, the combination is crushing. Landowners spend their rents on luxury imports and urban residences rather than on improving agricultural productivity; merchant capital circulates in usury and speculation rather than in industry; foreign monopolies repatriate profits rather than reinvest them locally. Baran documented this with empirical care: “the bulk of this surplus is not used to expand and improve productive plant and equipment.” Large portions flow abroad, are consumed conspicuously, or are absorbed by financial operations with no productive content.
Baran and Sweezy extended the argument in Monopoly Capital (1966): under monopoly capitalism, the surplus tends to rise as productive investment outlets contract, pushing capital toward financial rather than productive deployment. What this framework still required was a class analysis, that is, an identification of the specific social agent whose choices produce these outcomes. Vania Bambirra, writing from within the Latin American dependentist tradition, supplied it. She undermined two illusions at once: the expectation of an anti-imperialist alliance with a “progressive national bourgeoisie”, and the CEPAL developmentalist conviction that industrial capital would organically drive national transformation. Both misread the class that actually existed in Latin America. The big bourgeoisie there was not a frustrated national bourgeoisie awaiting the right conditions to invest productively. It was a class whose accumulation was constitutively articulated with imperialism–dominant domestically, subordinate internationally–whose material interests ran against the kind of development both traditions hoped it would lead.
Measuring where the surplus goes
The Baran Ratio measures the share of the economic surplus–GDP minus total compensation of employees–that reaches gross fixed capital formation: machinery, infrastructure, equipment, and the material foundations of productive capacity. This captures something that investment-to-GDP ratios obscure: dividing investment by total output conflates the surplus controlled by capital with the wage income earned by workers. The question Baran was asking is not how much of total output a country invests, but how much of the surplus that ruling classes control gets redirected toward productive accumulation–and how much does not. The two things can move in very different directions, and, in the periphery, they do so systematically.
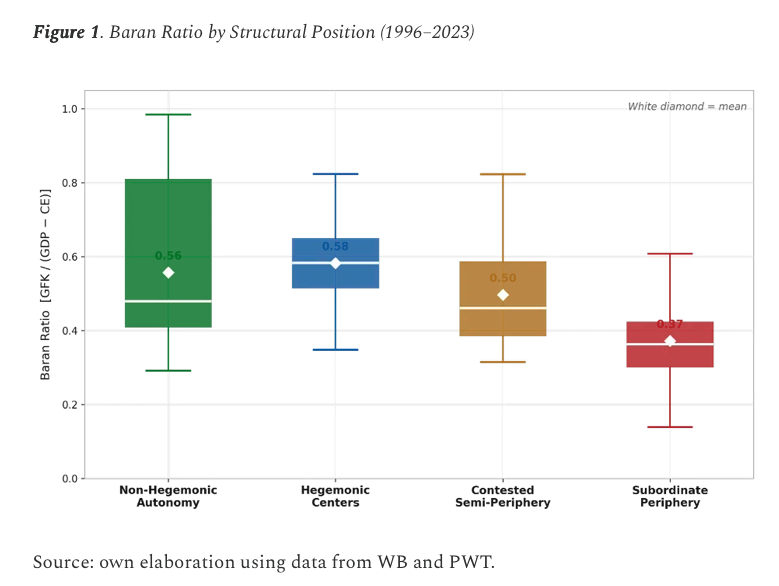
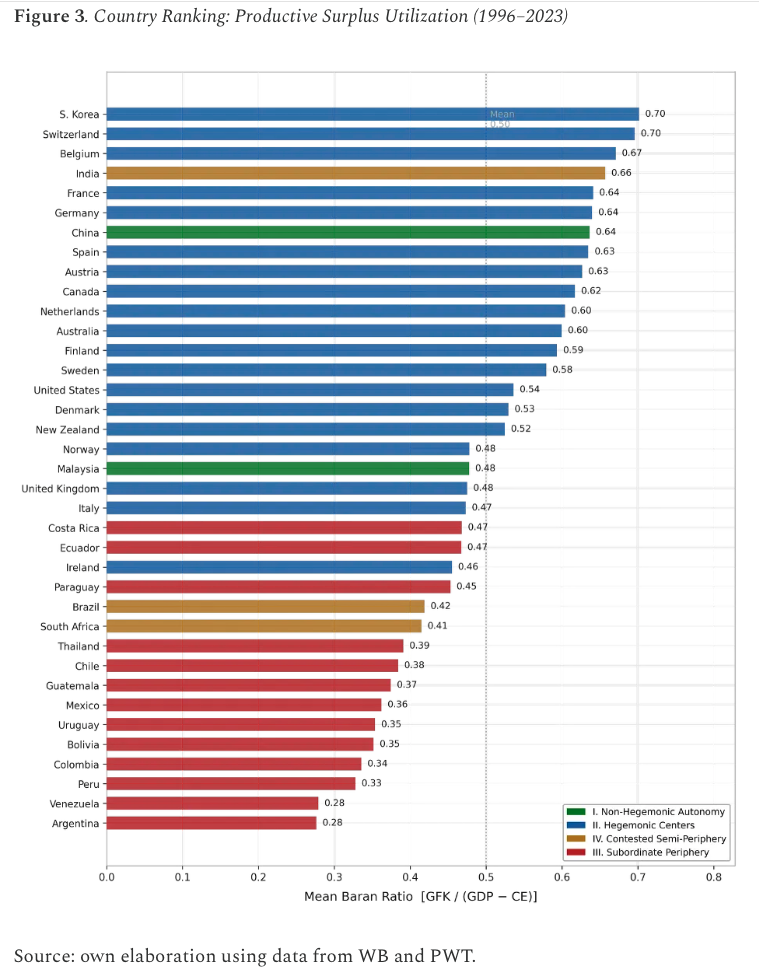
The global mean Baran Ratio across our 36-country sample is 50%–about half the surplus reaches productive investment. That average is less informative than what lies beneath it: a gradient that is not random, not the product of differential endowments or institutional accidents, but a structural expression of position in the global hierarchy of capital.
Over the full period 1996—2023, South Korea reinvests 70% of its surplus productively; China, 64%. But these full-period averages flatten a trajectory that has moved sharply. Since 2013–the year China peaked at 98% and began stabilising at a new structural floor–the picture is substantially different: China has averaged 88%, South Korea 74%, India 73%. Western economies, meanwhile, have moved in the other direction. Germany averaged 67% in 1996—2012; since 2013, it has averaged only 60%. France held at 63% and has since risen to 66%–an outlier in a group that has generally seen productive reinvestment compress as financialization deepens. The United States has remained stable at around 53—54% across both periods, reflecting the particular structure of American capital accumulation. At the bottom, Latin America’s Subordinate Periphery has averaged 36% across the full period and has not meaningfully improved: Argentina moved from 25% to 32% between the two sub-periods, Mexico from 37% to 34%.
What makes this hierarchy analytically significant is that it does not align with output per capita, resource endowment, or even nominal investment rates. It aligns with the degree to which the state has historically subordinated surplus allocation to productive ends, and, behind that, with the class configurations that made such subordination possible or foreclosed it. The correlation between the rate of surplus value and the Baran Ratio across countries is r = −0.778, with exploitation highest and productive reinvestment lowest. In the dependent nations, high exploitation and low reinvestment are not independent tendencies. They are two faces of the same class strategy.
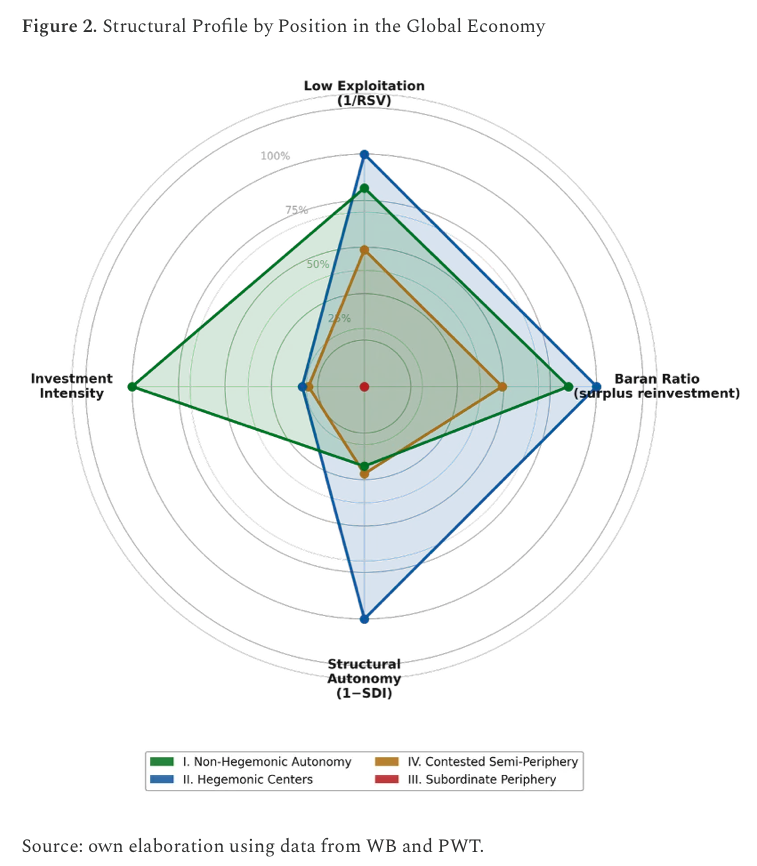
The radar chart makes visible what the aggregate numbers suggest but do not fully show: the structural profile of Western economies is not simply different from that of the periphery, it is constituted in relation to it. Arghiri Emmanuel’s theory of unequal exchange offers a crucial complement to the Baran Ratio. Where Marx analyzed exploitation at the point of production within a national economy, Emmanuel showed that exchange between nations with systematically different wage levels transfers value from low-wage to high-wage economies even in the absence of any explicit mechanism of coercion. The relatively lower surplus value rates in Germany and France, at 0.48 and 0.53, respectively, compared with 1.35 in Argentina and 1.73 in Peru, are not simply the result of more productive technology or stronger labour mobility in the centre. It is partly sustained by the terms on which Northern capital imports goods produced under conditions of super-exploitation in the South, capturing in the price differential a portion of the value produced under lower wage conditions. The low exploitation rate of the North and the high exploitation rate of the South are not independent phenomena–they are connected through the circuits of the world market. What Figure 2 shows as four distinct structural profiles is, from this angle, a single system with a hierarchical division of labour, surplus, and reinvestment.
Figure 3 ranks all 36 economies by their mean Baran Ratio over the period. The visual makes the regional clustering unmistakable: Latin American economies occupy the bottom of the distribution almost without exception, while East Asian and Western European economies concentrate at the top. The gradient is not a continuum–it has breaks that correspond to structural positions
China: what the opposite looks like
In 1996, China reinvested 29% of its surplus productively, below the Latin American mean at the time. The figure is worth holding for a moment: in the mid-1990s, Chinese workers produced a surplus that was, proportionally, less productively reinvested than in Argentina or Colombia. By 2008, the ratio had reached 60%, and by 2013, it peaked at 98%–virtually the entire surplus was redirected toward productive investment, a value unmatched in our dataset. By 2023, it had settled at 88%, still far above any comparable economy. What the trajectory describes is not simply growth but structural transformation: a threefold increase in the productive utilization of surplus over three decades, sustained across political cycles, financial crises, and shifting global conditions.
The mechanism behind this trajectory is not mysterious, but it requires careful specification. China’s Baran Ratio did not rise because of China’s transition from a socialist system to a capitalist system after the reform and openness. This is a Eurocentric explanation: all processes in the world must follow the logic of European modernity. China was not more efficient because market forces happened to favour productive investment. It rose because successive Five-Year Plans subordinated the allocation of surplus to explicit productive targets–not as technocratic exercises in resource allocation, but as instruments for integrating national value chains, developing domestic technological capacity, and progressively moving the productive structure up the ladder of complexity. Where Western economies since the 1970s channelled a growing share of surplus into financial valorization–shortening the circuit of capital, inflating asset prices, and progressively decoupling financial returns from productive activity–China’s state maintained the long circuit: surplus into productive investment, productive investment into expanded capacity, expanded capacity into a deeper integration of the national productive structure. The result is visible not only in the Baran Ratio but in the composition of Chinese exports, which moved from low-value assembly to high-complexity manufacturing over precisely the period in which the ratio climbed.
Giovanni Arrighi, in Adam Smith in Beijing, attributed China’s rise to the Smithian logic of the division of labour and market expansion. What the Baran Ratio shows is something different: the Chinese trajectory is driven not by exchange but by the systematic direction of surplus toward fixed capital investment–a logic that is closer to Marx’s analysis of expanded reproduction than to Smith’s account of commercial development.
This matters for the broader argument of this article because it illustrates what the framework that we have developed in our previous article, Building Sovereignity, captures through the productive dependency dimension of the SDI: the degree to which an economy controls its own productive structure, rather than occupying a subordinate position in value chains controlled from outside. China’s ascent was simultaneously a rise in the Baran Ratio and a reduction in productive dependency–the two processes are not independent. The capacity to reinvest the surplus productively and the capacity to develop an autonomous productive structure reinforce each other: investment deepens the value chain, and a deeper value chain generates the productivity gains that expand the investable surplus. This is the developmental dynamic that dependency theory predicted was possible under specific political conditions, and which the data confirms was achieved in China over three decades.
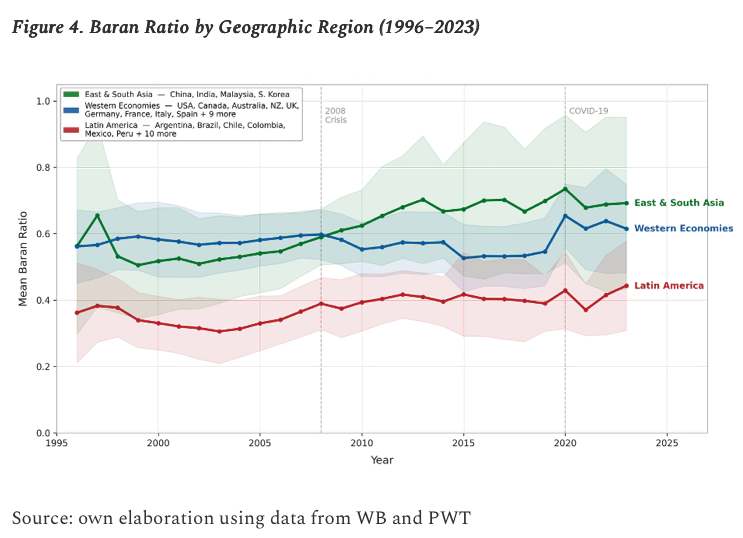
The 2008 crisis marked a visible inflection in the regional trajectories. For Western economies, the exit from the crisis did not restore the productive circuit; it deepened its disarticulation. The response of central banks and treasuries channelled extraordinary liquidity not toward productive investment but toward a new cycle of financial expansion, initially through quantitative easing and near-zero interest rates, and subsequently through the leveraged growth of technology platforms whose valuations rest less on productive capacity than on monopoly rents over data, attention, and digital infrastructure. The interlocking of big tech valuations with financial markets–and, increasingly, with the arms industry through defence contracts and dual-use technologies–has produced a form of capital accumulation that is simultaneously highly concentrated and structurally disconnected from the production of goods and services. The internal productive chains of Western capitalism, progressively outsourced since the 1970s and never reconstructed after the crisis, cannot absorb the surplus generated by financial expansion. The result is visible in the data: Western Baran Ratios, already declining before 2008, continued to compress afterward, while the financial sector’s share of corporate profits expanded. The surplus is being reinvested–but into circuits that inflate assets rather than productive capacity.
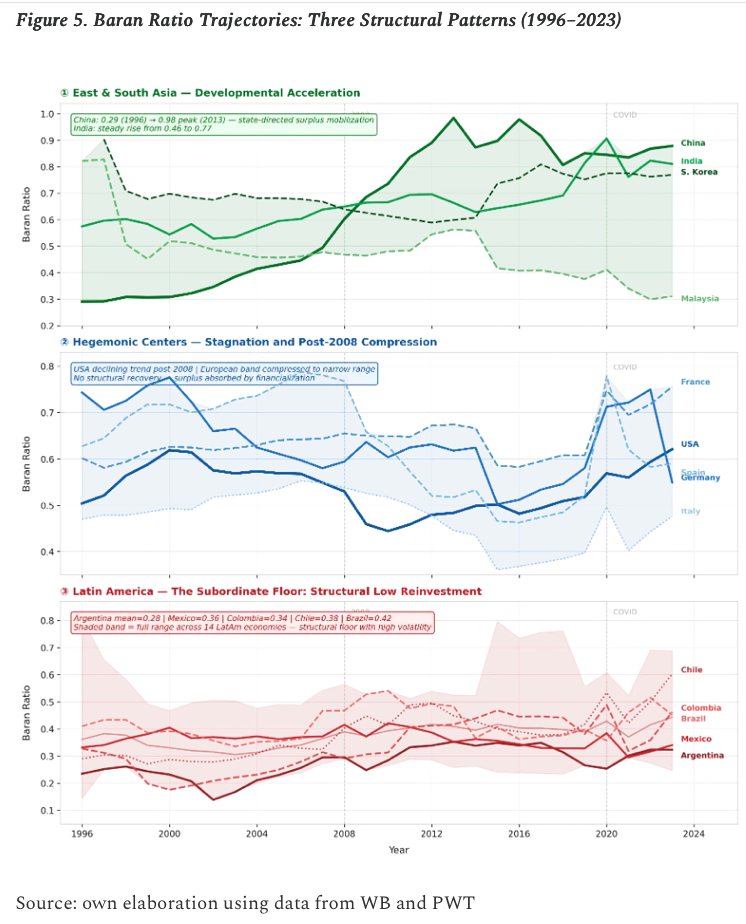
Argentina reinvests 28% of its surplus productively over the 28-year period, the lowest in the sample. Peru sits at 33%, Colombia at 34%, Mexico at 36%, and Chile at 38%. Germany averages 64% over the same period. France 64%. The United States 54%. Argentina allocates less than half of what Germany does, proportionally to the surpluses each economy generates, in a country that has spent half a century trapped in cycles of stagnation, debt, and deindustrialization. Brazil, at 42%, is the strongest performer in the region, and the gap with Argentina and Peru reflects the partial state capacity that Brazil has managed to preserve–public banking, Petrobras, BNDES–rather than any fundamental difference in class structure.
What makes these figures structurally distinct is not only the low reinvestment rate but the combination. Argentina’s workers produce 1.35 units of surplus for every unit they earn, an exploitation rate nearly double that of German or French workers (0.48 and 0.53, respectively). Peru is more extreme still: a rate of surplus value of 1.73, meaning workers generate almost three times their own wage in surplus, while the economy directs only 33% of that surplus toward productive investment. Colombia (RSV 1.56, Baran 34%), Mexico (RSV 1.35, Baran 36%): the pattern repeats across the region with a regularity that rules out coincidence.
Ruy Mauro Marini’s Dialéctica de la dependencia (1973) identified the mechanism connecting these two facts. In dependent economies, local capital faces a structural disadvantage against the technological superiority of foreign firms. It compensates through what Marini called super-exploitation of labour: the intensification of work beyond its normal limits, the extension of the working day, and the reduction of wages below the value of labour power itself–not just the extraction of surplus value, but the compression of wages below what workers need to reproduce themselves. Super-exploitation magnifies the surplus extracted. But this enlarged surplus does not return to expanding productive capacity. Because dependent production is oriented toward external markets rather than the domestic consumption of workers–who are simultaneously the primary producers and the systematically excluded consumers–the circuit of capital in the periphery separates production from the realization of value. The surplus finds its outlet in exports and in the luxury consumption of the classes that appropriate it, not in expanded reproduction of the domestic economy. The wages compressed by super-exploitation cannot sustain an internal market, and the surplus magnified by super-exploitation does not fund productive investment. Both mechanisms reinforce each other in a self-reproducing loop that our data registers across thirty years.
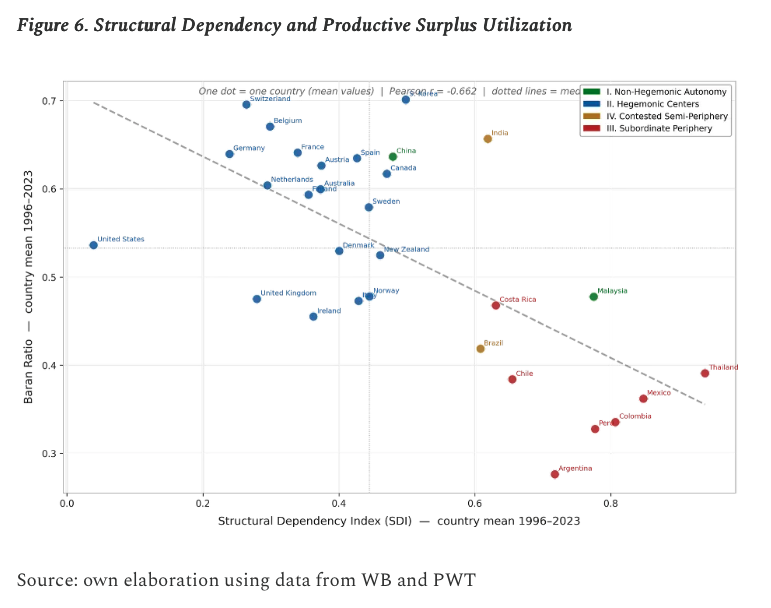
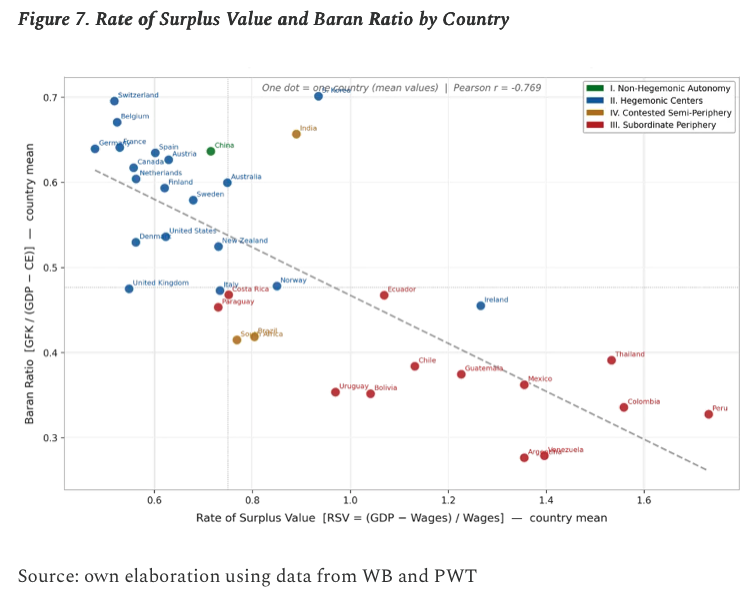
This is not exclusively a Latin American story. Walter Rodney’s How Europe Underdeveloped Africa (1972) showed that the systematic extraction and misdirection of surplus from colonised economies was the historical foundation on which both European development and African underdevelopment were simultaneously constructed. The colonial social structures that emerged from that process–classes whose wealth derived from resource extraction and intermediation rather than productive development–carried the same logic into the post-independence period. South Africa’s Baran Ratio of 41%, alongside an RSV of 0.77, registers the accumulated weight of a class formation shaped by that history. The Double Drain, in this sense, is not an economic phenomenon with a political dimension; it is a political-historical construction that expresses itself through economic numbers.
The wage share across the Subordinate Periphery averages 46%, compared to 61% in advanced Western economies. More is taken from labour than in the centre. Less reaches the productive apparatus than anywhere else in the sample. And the productive backwardness that results from low investment perpetuates the conditions that make super-exploitation necessary–closing the circle that Marini described as the dialectic of dependency.
A class without a national project
The standard explanations–institutional weakness, policy uncertainty, unfavourable business climates–treat symptoms as if they were causes. The data shows a class pattern, and the class pattern has a logic.
Baran documented where the surplus goes when it does not go into productive investment. Foreign monopolies operating in underdeveloped countries, he showed, do not reinvest their profits locally: “that portion of which the monopolist combines takes the largest share is not used for productive purposes. It is not reinvested in their own enterprises, nor does it serve to develop others.” What does not flow abroad “is used in almost the same way as the landowning aristocracy uses it–luxury consumption, urban real estate, and financial speculation. And: “strong sums are taken abroad, held as protection against currency devaluation or as a reserve to ensure a decent retirement in case of social and political disturbances.” Capital flight is rational behavior given the structural position of the class that practises it.
The domestic bourgeoisie operates by the same calculus. Its accumulation does not depend on developing the national productive apparatus but on intermediating resource extraction, brokering foreign investment, and managing the financial circuits through which surplus exits. Bambirra showed this was not bad luck or misguided policy but the structural outcome of how capitalism was inserted into Latin America from the beginning. The propertied classes that emerged from that history have no organic interest in productive national development–they have an organic interest in the conditions that make their existing accumulation possible: the conditions of dependency.
This is why associated development has produced the same result across different political cycles. Argentina’s 28%, Mexico’s 36%, and Colombia’s 34% are not the consequence of bad policy choices. They are the consequence of treating as a subject of development a class whose power rests on the combination of domestic dominance and international subordination that development would dissolve. Keynes observed, from a different political position entirely, that capital responds to the cold calculation of short-term advantage rather than to national projects. In the periphery, that calculation runs against productive reinvestment with a consistency that no incentive structure has managed to disrupt.
The state and the surplus
The data also shows the other side. Under different political configurations, the surplus has been redirected. What separates the trajectories at the top of our distribution from those at the bottom is not resources, geography, or endowment. It is the degree to which the state has developed the capacity to impose a different logic of surplus allocation–and the social and historical conditions that made that capacity possible or foreclosed it.
Samir Amin called this delinking: not withdrawal from the world economy, but the subordination of external economic relations to internally defined developmental priorities. The concept operates simultaneously as a diagnosis and as an orientation–it names what successful cases have in common and identifies the structural condition that autonomous development requires. Where states have retained or built institutional instruments to condition how capital uses its earnings–public banking, capital flow regulation, strategic industrial policy, public ownership in commanding sectors–the surplus has consistently reached productive investment at higher rates. The framework that we are developing captures this through the State Mediating Capacity index, which operationalises the degree to which state institutions can act with relative autonomy from the immediate interests of the dominant fractions. An autonomy that is never given by institutional design but won through the specific configurations of social forces that particular historical moments produce.
The Contested Semi-Periphery–Brazil, India, South Africa–occupies the most analytically significant terrain precisely because it demonstrates that the outcome is not predetermined. Brazil at 42%, India at 66%: these are not accidental. They reflect the partial survival of developmental state instruments alongside the persistent constraints of peripheral insertion. These economies have enough institutional capacity to redirect the surplus differently, yet not enough to do so consistently–caught between the possibilities their state apparatus opens and the class configurations that narrow them. That tension is not a transitional phase on the way to resolution. It is the permanent condition of this position in the hierarchy, where the balance of class forces remains genuinely open in ways it is not at either extreme.
The bourgeoisie’s systematic failure to lead productive national development in Latin America is not a character defect or a cultural trait; it is the predictable expression of a class whose position in the global hierarchy is organised around extracting and transferring value rather than expanding the productive basis on which all other possibilities depend. Bambirra understood this not as a moral judgment but as a structural analysis: a class constituted through dependency cannot become the agent of its dissolution without ceasing to be what it is. This does not foreclose alliances or coalitions with specific capitalist fractions under specific conditions, but it places those alliances in their proper subordinate position–as instruments of a developmental project whose direction and social content must be defined by other forces if it is to be defined at all.
The Baran Ratio measures, year by year and country by country, the outcome of these struggles over the destination of the surplus. What the data cannot resolve is the open question of the present: whether the partial institutional capacities that still exist in parts of the Global South will be expanded, consolidated, or progressively eroded. That depends on processes the ratio does not capture: on organisation, on coalition, on the political intelligence of forces that understand what the numbers mean. Thirty years of evidence across 36 economies establishes the structural baseline. What gets built on top of it, or against it, remains to be determined.